
While working on a blog about identity theft and how SIM binding helps reduce such digital fraud, I realized I had only scratched the surface. Fraud prevention today needs to go beyond static rules and traditional methods. It’s time we shift focus toward smarter, adaptive, and user-aware systems, ones that learn, evolve, and respond in real-time. Fraudsters are getting faster and more sophisticated with the surge in mobile banking, and our defenses must be just as agile, personal, and intelligent. So, let’s uncover the limitations of traditional measures and explore the idea of developing a more robust and adaptive fraud detection framework, as it's projected to reach $14 billion market cap by 2032, as compared to $1.6 billion global valuation in 2023 (GrandViewResearch 2022). The US and European majors are leading the evolution, followed by Asia.
The rising complexity of digital banking fraud has forced institutions to look for intelligence-driven solutions like behavioral biometrics within the cybersecurity framework. Although most of the financial institutions have implemented Artificial Intelligence for fraud detection, they are largely aloof from implementing behavioral biometrics. According to Peters' report, just 22 per cent of the institutions globally utilize behavioral biometrics.
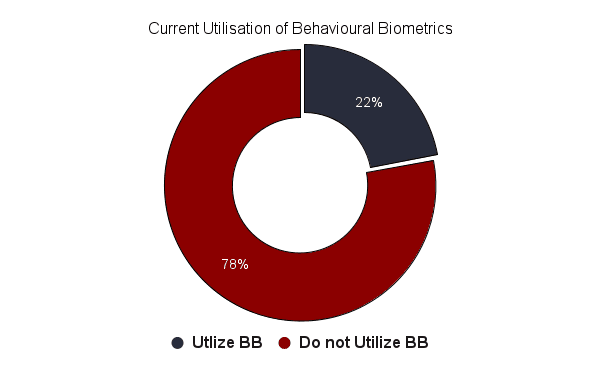
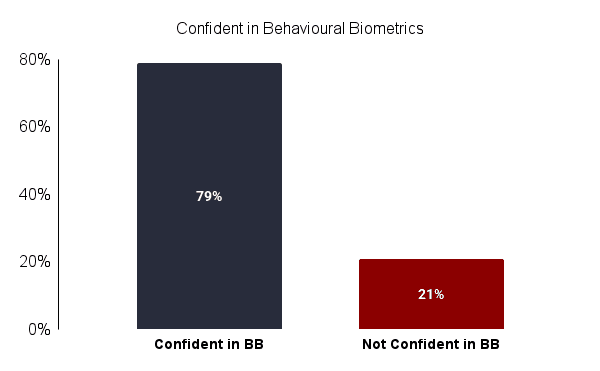
As we can infer from the graph above, despite 79 percent being confident about behavioral biometrics being a promising extension of artificial intelligence, only 22 percent actually utilize it. Although the global implementation of AI for fraud detection has exceeded 75 per cent across financial institutions, the deployment of behavioral biometrics remains limited. This deviation suggests that while the perception is favorable, there are risks and challenges that are slowing the adoption.
What is Behavioral Biometrics?
It is a method to identify or verify individuals based on unique patterns of how they interact with the application or device, beyond their login credentials, such as fingerprint, password, OTP, or facial recognition. Behavioral biometrics complements other security measures like SIM binding by continuously verifying users through their unique interaction patterns. While SIM binding secures the device, behavioral biometrics ensures the right person is using it, together forming a smarter, stronger defense against fraud.
So this continuously analyzes the passive behavior of users, such as:
- Typing speed and rhythm
- How a user taps a screen or moves a mouse
- Scrolling Patterns
- Angle, pressure, and speed of mobile touches
- GPS movement
- Session navigation pattern
How does it work in real-time?
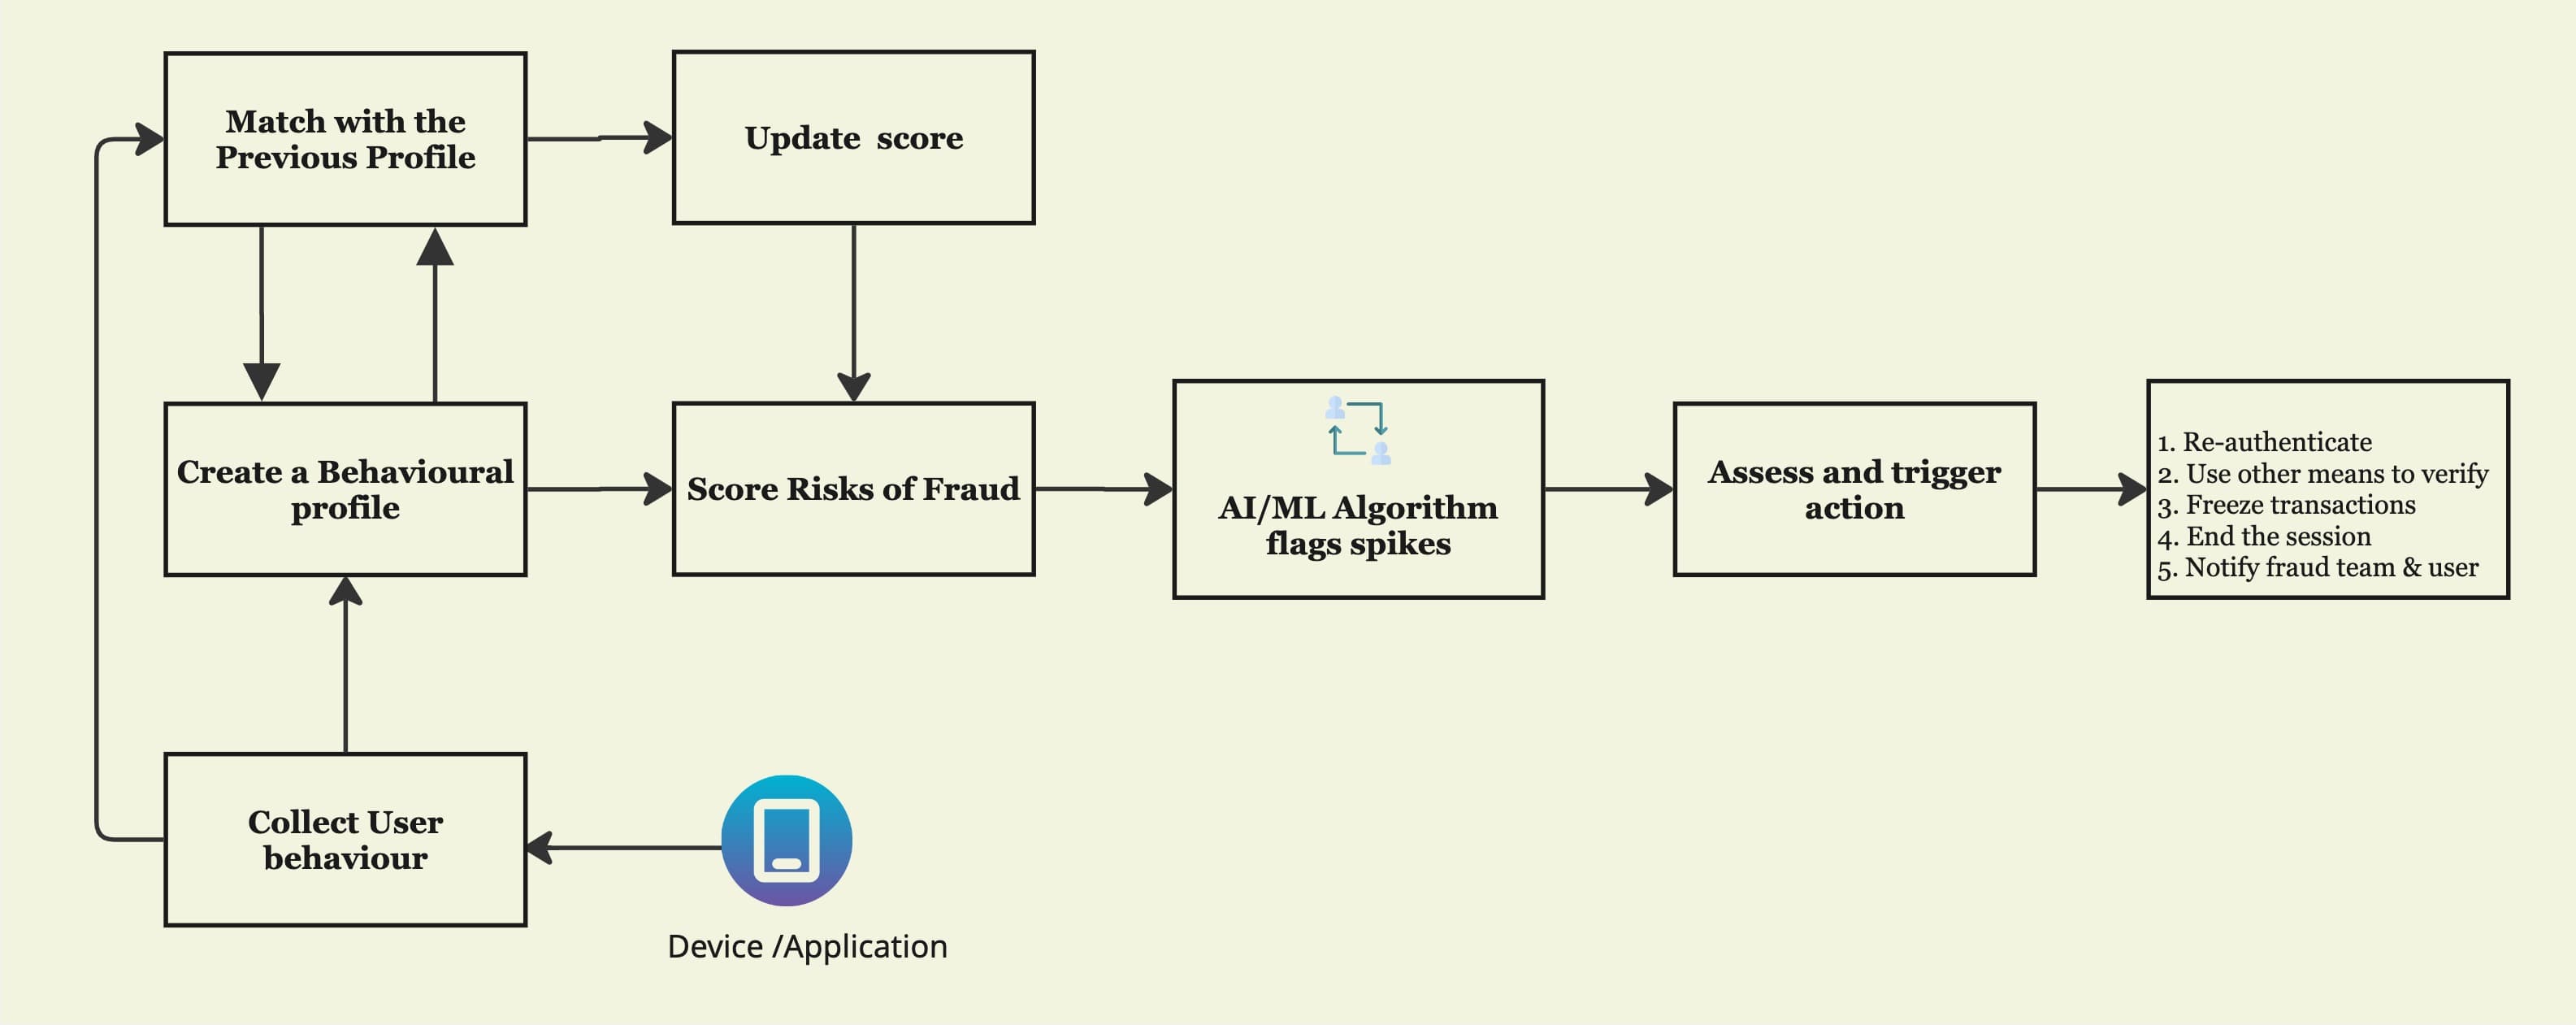
1. Use session begins
a. Once a user logs in and starts a payment, behavioral biometrics starts collecting data in the background
2. Baseline behavioral profile
a. The system has already built a behavioral profile for all returning users based on their past interactions
b. For a new user, it scores the risk and improves over time with the collection of more data
3. AI/ML Analysis
a. The algorithm continuously matches a user's behavior in real-time
b. If anything seems off, like an abrupt change in typing speed or other deviations from the biometric profile, it scores the risk metric
4. Fraud prevention
a. If the above score flags the behavior as suspicious, the system prompts the user for any of the following actions based on the severity
i. Re-authenticate (fingerprint or face recognition, or OTP)
ii. Verify by other means, Ivrs verification
iii. Freeze transaction
iv. End the session
v. Block the device/app access for 24 hrs or so
vi. Notify the fraud team and the user
Why is it powerful and effective in fintech?
- Continuous and Passive: There’s no extra input required from the users’ point of view, which makes it invisible yet effective.
- Nearly Impossible to Spoof: Unlike the situations where the credentials are stolen or OTP is intercepted, or the device is cloned, it’s nearly impossible to replicate the human behavior, like (swipe pattern or typing speed).
- Real-time response to threats: the system immediately analyses the risk score spike and takes action in real-time rather than after the damage is done.
- Real-world fraud use cases:
Account takeover: Even if the scamster has the account access, their behavioral analytics won’t match the actual user’s, and this will be flagged before any fraudulent activity.
Synthetic Identity fraud: Bots or scripts used to simulate user behavior will be caught due to erratic or uniform behavior.
Multi-device session tracking: If the same user starts behaving differently on different devices, then it is assumed the account is compromised.
Payment fraud monitoring: Unexpected spike in transaction amounts results in fraud alerts.
- Financial institutions are betting high on it (Bloomberg Intelligence, 2024):
VISA has committed $12 billion to Data & AI initiatives over 5 years
Mastercar’s collaboration with Feedzai
What are the associated Challenges in implementation?
- Legacy infrastructure: The legacy banking system architecture doesn’t support the implementation and requires a complete overhaul, which will incur significant costs to institutions.
- Regulatory uncertainty: Lack of clear guidelines from the governing body of financial institutions
- Data privacy concern: Financial institutions must be GDPR and PSD2 compliant for secure and consent-based data collection, processing, and preservation.
- False Positives: An early-stage system might flag legitimate user behavior until the algorithm is fully trained
- Integration complexities: Computational intensity required to process continuous behavioral data demands a high-performing, scalable system with a real-time response architecture.
Conclusion
Behavioral biometrics is quietly transforming fraud detection in fintech, providing a seamless, intelligent, and real-time layer of protection that operates unobtrusively in the background. As fraud methods grow more sophisticated, particularly with the rise of AI-generated identities, this approach is increasingly vital for safeguarding both users and institutions by finding a middle ground on privacy and regulatory concerns.