
The innovation narrative in the insurance sector has shifted decisively. The era of loose experimentation and flashy Proof of Concepts (PoCs) is over. The insurance industry has transitioned from mere AI adoption to a hard-nosed era of accountability, execution, and scale.
Driven by advanced machine learning models and alternative datasets (such as telematics, IoT, and real-time transaction history), the global AI in insurance market is projected to skyrocket from $13.45 billion to $154.39 billion, exhibiting a massive CAGR of 35.7%.
Yet, this rapid acceleration faces a significant bottleneck: the "Black Box" dilemma.
Deep learning models and complex gradient-boosted trees offer unparalleled predictive accuracy, minimizing underwriting leakage and optimizing loss ratios. However, their internal logic is often entirely opaque. As global regulatory bodies crack down on algorithmic bias and secret pricing models, insurers face a high-stakes challenge. How do you leverage hyper-accurate AI risk modeling without landing in regulatory crosshairs?
The answer lies in Explainable AI (XAI)—the indispensable framework that balances underwriting precision with bulletproof compliance.
The Core Friction: Hyper-Accuracy vs. Strict Governance
For modern Chief Underwriting Officers (CUOs) and data teams, the temptation to build increasingly complex models is clear. According to industry data, 62% of insurers report that AI has significantly improved underwriting quality and slashed fraud rates. Furthermore, moving away from legacy, paper-based workflows to AI-driven automated underwriting systems (AUS) drastically improves efficiency—reducing average policy issuance time from 33 days down to just 12.5 days.
But mathematical accuracy cannot come at the expense of legal transparency. The regulatory landscape has hardened globally, transforming AI explainability from a "nice-to-have" data science feature into a strict compliance mandate:
- The EU AI Act Categorizes AI systems used for insurance risk assessment and pricing as high-risk. This classification mandates strict data lineage, continuous human oversight, and absolute auditability. Non-compliance is catastrophic, carrying potential fines of up to 7% of global annual turnover.
- The NAIC Model Bulletin (US): The National Association of Insurance Commissioners (NAIC) explicitly requires insurers to maintain comprehensive model risk management frameworks. Insurers must prove their algorithms do not result in disparate impacts or proxy discrimination against protected classes (such as race, gender, or zip codes).
- State-Level Action: Legislation like California’s Physicians Make Decisions Act and strict New York Department of Financial Services (NYDFS) circulars mandate that if AI contributes to an adverse underwriting decision, the insurer must provide a plain-language explanation to the consumer within narrow windows (e.g., 15 days).
Relying on an unexplainable model is no longer just a technical limitation; it is a compliance time bomb.
What is Explainable AI (XAI) in Underwriting?
Explainable AI does not mean dumbing down your predictive models or reverting to outdated, rigid "if-then" rule engines. Instead, XAI utilizes mathematical frameworks applied on top of complex machine learning models to translate abstract algorithms into clear, human-intelligible rationales.
When auditing an AI-generated risk score, data teams and compliance officers rely on three core XAI methodologies:
1. SHAP (SHapley Additive exPlanations)
Based on cooperative game theory, SHAP calculates the exact marginal contribution of each feature to a specific outcome. For instance, if a commercial property applicant is assigned a high-risk score, SHAP can explicitly detail that 40% of the score was driven by building age, 35% by proximity to a wildfire zone, and 25% by local crime indexes.
2. LIME (Local Interpretable Model-agnostic Explanations)
While SHAP looks at global model behavior, LIME zeroes in on an individual decision. It builds a localized, simplified model around a single applicant’s data point to explain exactly why that specific individual was denied a standard rate or fast-tracked for straight-through processing (STP).
3. Counterfactual Explanations
This approach provides "what-if" scenarios that turn automated decisions into actionable insights. It establishes the minimum change required for a different outcome—for example: "If the applicant's fleet telematics hard-braking events decreased by 15%, the auto policy premium would drop from Tier C to Tier B."
Empowering Three Crucial Insurance Stakeholders
Implementing XAI is a strategic move that delivers immense value across three distinct organizational layers:
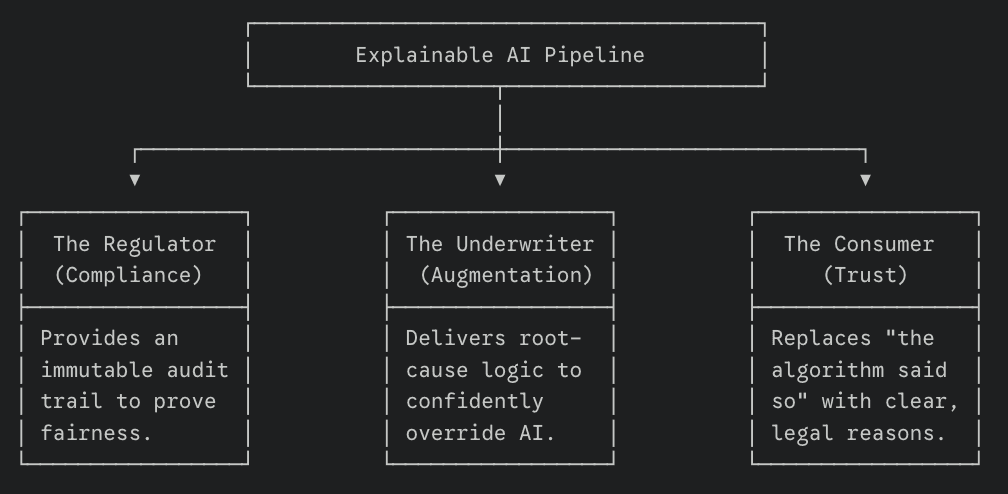
1. The Regulator (Compliance & Legal)
XAI provides compliance officers with an immutable, traceable audit trail. If a regulatory body questions a carrier's pricing structure, XAI proves that the model's decisions are rooted in legitimate, actuarial risk factors rather than illegal proxies for discrimination.
2. The Human Underwriter (Augmented Intelligence)
AI is not replacing underwriters; it is augmenting them. When an advanced model flags an application for a steep premium increase, an explainable interface shows the underwriter the exact root-cause logic. This allows the human professional to validate the decision, catch data anomalies, or confidently override the system when necessary.
3. The Consumer (Brand Trust)
When a long-term customer asks why their home premium suddenly jumped, replying with "our algorithm calculated it" destroys brand equity and invites legal complaints. XAI allows customer service and distribution networks to provide clear, legally compliant, and transparent explanations, maintaining consumer trust.
Actionable Blueprint: Striking the Perfect Balance
To scale AI underwriting safely, carriers must transition from pure data science to strict AI governance. Consider this operational roadmap:
- Establish Day-Zero Governance: Do not attempt to retrofit explainability into a model that is already live in production. Build SHAP/LIME pipelines directly into your MLOps infrastructure during the initial training phase.
- Prioritize Parsimony Over Complexity: A slightly less complex, highly interpretable ensemble model that compliance clears in a week is infinitely more valuable than a hyper-complex neural network that sits stalled in legal review for nine months.
- Implement Continuous Bias & Drift Monitoring: Real-world data changes constantly. Set up automated dashboards that monitor your production models weekly for data drift and statistical fairness metrics (such as equalized odds and disparate impact ratios).
- Maintain Human-in-the-Loop (HITL) Workflows: Route high-volume, low-risk policies through Straight-Through Processing (STP) to capture operational efficiency. However, ensure that boundary cases, complex risks, and adverse actions are always routed to an underwriter equipped with an XAI dashboard.
Conclusion
Balancing underwriting accuracy with regulatory compliance is a core business imperative. Carriers that rely on unexplained face severe regulatory penalties, model deactivation, and eroding consumer trust.
Conversely, forward-thinking insurers are utilizing Explainable AI to build a defensible, highly efficient, and transparent underwriting ecosystem. By proving why and how your AI makes decisions, you don't just satisfy the regulators—you unlock the confidence needed to scale automation safely.