

Editor’s Note: This article was originally written by Amrit Saluja and published in December, 2025. It was revised and updated by Shivangi Agarwal in August, 2026 to include current technologies, implementation practices, industry requirements, and examples. The technical content was reviewed by Kumar Pratik, Founder & CEO, and Kunal Kumar, Chief Revenue Officer
Key Takeaways
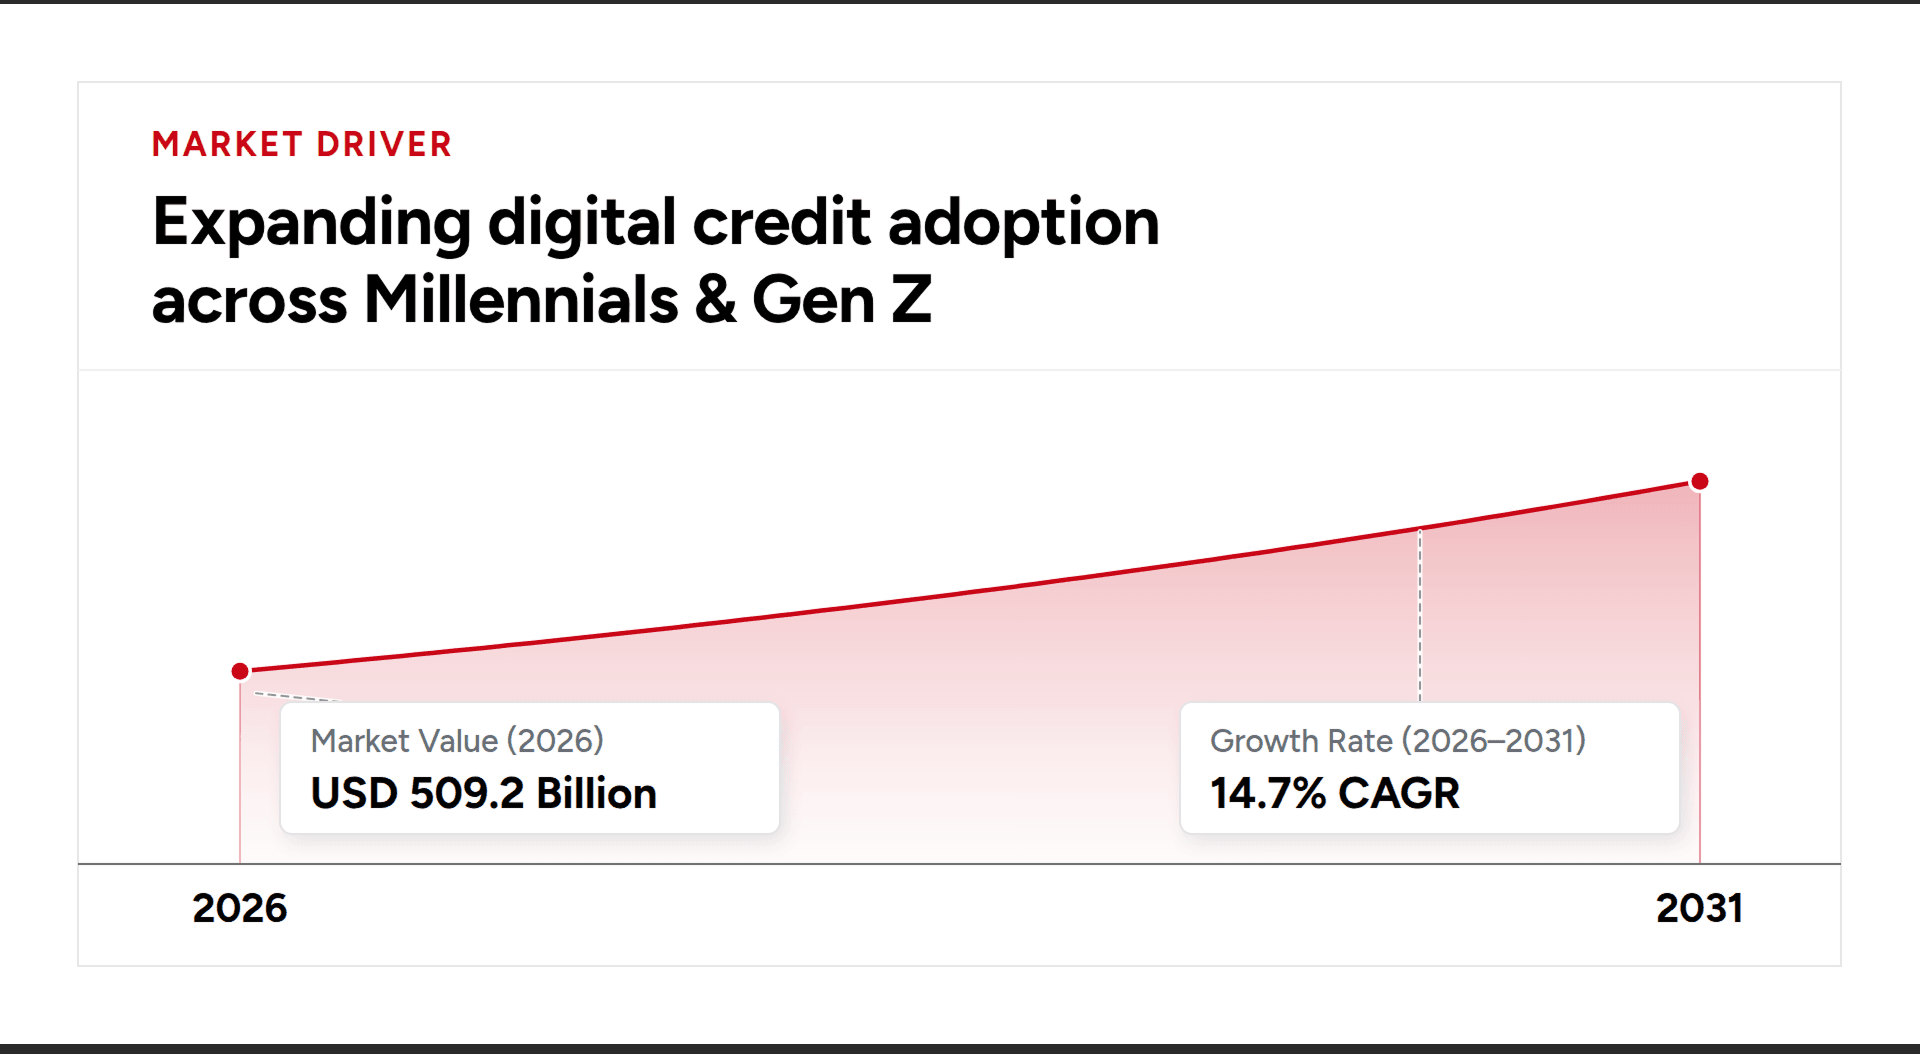
- The global BNPL payment market is expected to reach US$509.2 billion in 2026 and grow at a 14.7% CAGR through 2031, positioning it as one of fintech’s fastest-growing segments.
- Compliance and scalability remain the two pillars of Buy Now, Pay Later app success, as US regulators tighten oversight and platforms require strong data protection and adaptable infrastructure to sustain profitability.
- Gen Z and millennials continue to lead BNPL adoption in the US, with 59% of Gen Z and 58% of millennials using BNPL, compared with 52% of Americans overall.
- BNPL ROI depends on risk control and user retention. AI-based credit scoring and personalized repayment experiences can reduce defaults and improve lifetime value, turning compliance investments into ROI accelerators.
The digital economy is changing the very idea of credit, transforming payments into relationships of trust. What began as a convenient checkout option—“split your payment in four”—has grown into one of the fastest-moving sectors in fintech. According to 2026 market estimates, the global BNPL services market is valued at approximately US$750 billion in 2026 and is projected to reach US$1.64 trillion by 2031, growing at a 16.76% CAGR.
Younger consumers continue to lead BNPL adoption. A 2026 industry analysis found that 59% of Gen Z and 58% of millennials in the US used BNPL in 2025, compared with 52% of Americans overall.
Yet, beneath the rapid adoption lies a fault line for fintech enterprises. The opportunity is vast, but so are the demands of compliance, scalability, and ROI. Regulators are treating BNPL platforms more like credit providers, insisting on data-protection frameworks, transparent disclosures, and lending-risk controls. At the same time, brand trust hinges on infrastructure that can scale to millions of users without outage. And investors demand growth, profitable unit economics, low default rates, and clear lifetime-value curves.
Source: Global News Wire
For founders and product leads who aim to build a BNPL platform that lasts, success will hinge on three pillars:
- Building a regulatory-ready architecture,
- Scaling infrastructure for exponential growth, and
- Turning compliance and risk-visible investments into meaningful ROI.
This guide unpacks those pillars—covering cost structures, compliance frameworks (including PCI-DSS), scalable cloud-native architectures, and ROI modelling—so you can move beyond the hype and build a sustainable BNPL business in the U.S. market.
Why BNPL App Development Is a Smart Investment for Businesses Today
The BNPL market is maturing under increased regulatory pressure. Pay Later option providers are facing compliance standards comparable to traditional credit card companies. This trend is already separating serious players from opportunistic ones. The businesses building strong risk and fraud frameworks early are setting themselves up for sustainable growth.
While these regulations tighten, the market opportunity remains open—the Global BNPL market is expected to reach USD 681.13 billion by 2033—but the window for establishing leadership is narrowing as regulatory requirements solidify and operational barriers rise.
The strategic value to BNPL Business growth lies in understanding the following areas:
- Expanded customer access,
- Incremental transaction volume,
- And higher order values.
BNPL also reaches underserved segments (Millennials and Gen Zs) and converts purchases that would otherwise be abandoned. McKinsey research indicates that 61% of BNPL transactions represent new business rather than substitution from existing payment methods.
For Fintech enterprises, this means genuine revenue expansion, improved conversion rates, and competitive differentiation in markets where payment flexibility has become a customer expectation. Success requires treating compliance and risk management as foundational investments.
Customers choose predictability over credit. BNPL gives businesses a direct way to meet that expectation while controlling conversion, risk models, and repayment visibility. When companies build BNPL themselves, they don’t just improve checkout—they strengthen loyalty and reduce long-term acquisition costs
 Kunal KumarChief Revenue Officer
Insight: BNPL users return more often when repayment terms are clear and consistent. Owning the BNPL experience lets brands convert that trust into higher lifetime value.
Buy Now Pay Later App Development Like Klarna or Tabby in the USA: A Complete Guide
12 Must-Have Features of a Modern BNPL App
As BNPL becomes a mainstream credit and checkout option, the competitive edge lies in building a system that balances compliance, scalability, and experience. Below are the 12 essential features that define a successful BNPL platform.
1. User Onboarding & KYC Verification
BNPL platforms handle credit at scale, which makes identity verification and eligibility assessment non-negotiable from a risk and regulatory perspective. A modern onboarding system must support multi-layer sign-up via email, mobile, and ID matching, while automating KYC and AML checks through providers like Onfido or Trulioo. Bank account verification and fraud detection should be embedded in the flow to ensure only legitimate users enter the system. This builds user trust, ensures legal compliance, and minimizes risk exposure from the first interaction.
2. Payment Gateway & Checkout Integration
Checkout integration in Buy Now Pay Later Apps enables users to split payments instantly and merchants to boost conversions at the point of sale. The platform must offer "Pay-in-4" or custom installment options with instant approval powered by API-based verification. Integrations with processors like Stripe, Adyen, or proprietary payment systems ensure compatibility across merchant platforms. Seamless checkout experiences increase merchant sales and drive user adoption by removing friction at the moment of purchase. GeekyAnts' fintech teams have delivered multi-country payment gateway integrations for large-scale platforms.
3. Repayment & Installment Management
Transparent repayment management reduces defaults and improves user satisfaction by keeping customers informed and in control. The system should provide dynamic payment calendars with automated reminders, support both auto-debit and manual repayment options, and automate late fees with proactive alerts. Clear visibility into upcoming payments and flexible repayment options ensures users stay on track, which reduces collection costs and improves portfolio health.
4. Credit Scoring & Risk Engine
Accurate credit assessment protects both revenue and compliance by ensuring that lending decisions are based on reliable data. The platform must incorporate AI or rule-based scoring models, integrate with credit bureaus like Experian and Equifax, and include fraud analytics with risk visualization dashboards. This minimizes defaults, improves lending accuracy, and sustains profitability by aligning credit offers with actual user risk profiles. GeekyAnts' experience with AI-driven decision engines enhances BNPL risk evaluation accuracy.
5. Transaction History & Analytics
Users and merchants need complete visibility into their financial interactions to build trust and manage reconciliations. The platform should provide detailed transaction logs and repayment summaries, spending trend analysis, and exportable reports in formats like PDF and CSV. This transparency simplifies merchant operations and gives users confidence that their financial data is accessible and accurate.
6. Notifications & Alerts
Real-time communication prevents missed payments and improves engagement by keeping users informed at every stage of the transaction lifecycle. The system must support push notifications and email reminders for upcoming dues, transactions, and approval alerts, and promotional updates for limited offers. Consistent communication improves repayment rates and keeps users active within the ecosystem.
7. Merchant & Admin Dashboard
Operational control drives merchant retention and BNPL growth by providing the tools needed to manage transactions, settlements, and performance. The dashboard should support merchant onboarding and KYC, transaction tracking with refund and settlement workflows, and revenue analytics with performance insights. Data-driven visibility helps merchants understand how BNPL impacts their sales and allows administrators to monitor system health. GeekyAnts' Fintech and FleetEdge case studies highlight their ability to build multi-role dashboards with real-time visibility.
8. Security & Compliance Modules
BNPL is a financial product, which means compliance with data protection and lending laws is central to sustainability. The platform must implement AES-256 encryption and tokenization, OAuth 2.0 authentication, and built-in frameworks for GDPR and CFPB compliance. Fraud detection systems should run continuously to identify suspicious activity before it impacts users or merchants. These measures reduce regulatory risk and enhance customer confidence in the platform.
9. Customer Support & Dispute Resolution
Dispute handling and user support impact brand trust more than marketing does, particularly when financial transactions are involved. The system should offer in-app chat, ticket management, refund automation, along with complaint tracking and escalation workflows. Feedback capture mechanisms allow the platform to improve service quality over time. Strong support capabilities improve retention, reduce churn, and ensure customer protection.
10. Analytics & Reporting Suite
Real-time analytics turn data into actionable insights for growth and compliance by consolidating information across users, merchants, and transactions. The platform must provide revenue dashboards and default-rate reports, operational and customer behavior analytics, and ROI monitoring tools. Leadership teams rely on these insights to make informed, data-backed decisions about product development, risk management, and market expansion. GeekyAnts builds real-time analytics layers that consolidate user, merchant, and transaction data into actionable dashboards.
11. Loyalty Programs & Rewards
As BNPL competition intensifies, retaining users is as vital as acquiring them, and loyalty programs help encourage repeat usage. The platform should offer reward points for timely repayments, tiered loyalty levels like Silver, Gold, and Platinum, cashback and referral bonuses, and gamified repayment milestones. These features improve repayment behavior, build brand loyalty, and create a differentiated user experience. GeekyAnts' UX-first projects like WaxBuddy demonstrate expertise in gamified engagement and loyalty-based design.
12. Integration with Other Apps & Ecosystems
BNPL thrives when integrated into user and merchant ecosystems, making payments an embedded experience rather than a separate task. The platform must support e-commerce plugins for Shopify and WooCommerce, wallet and bank integrations with Apple Pay, Google Pay, and Plaid, and connections to CRM, ERP, and accounting tools. Open APIs for third-party developer extensions expand reach and strengthen partnerships, positioning BNPL as part of a broader fintech ecosystem. GeekyAnts' Fintech Global Payment Processing platform showcases how strategic API integrations drive multi-region BNPL scalability.
Every BNPL platform must balance user trust, compliance, and growth readiness. These 12 features form the backbone of any scalable BNPL ecosystem—from user onboarding to loyalty retention and ecosystem integration.
BNPL ROI Forecasting: How U.S. Fintechs Can Balance Compliance, Cost, and Scale
Formula-wise, ROI can be expressed as:
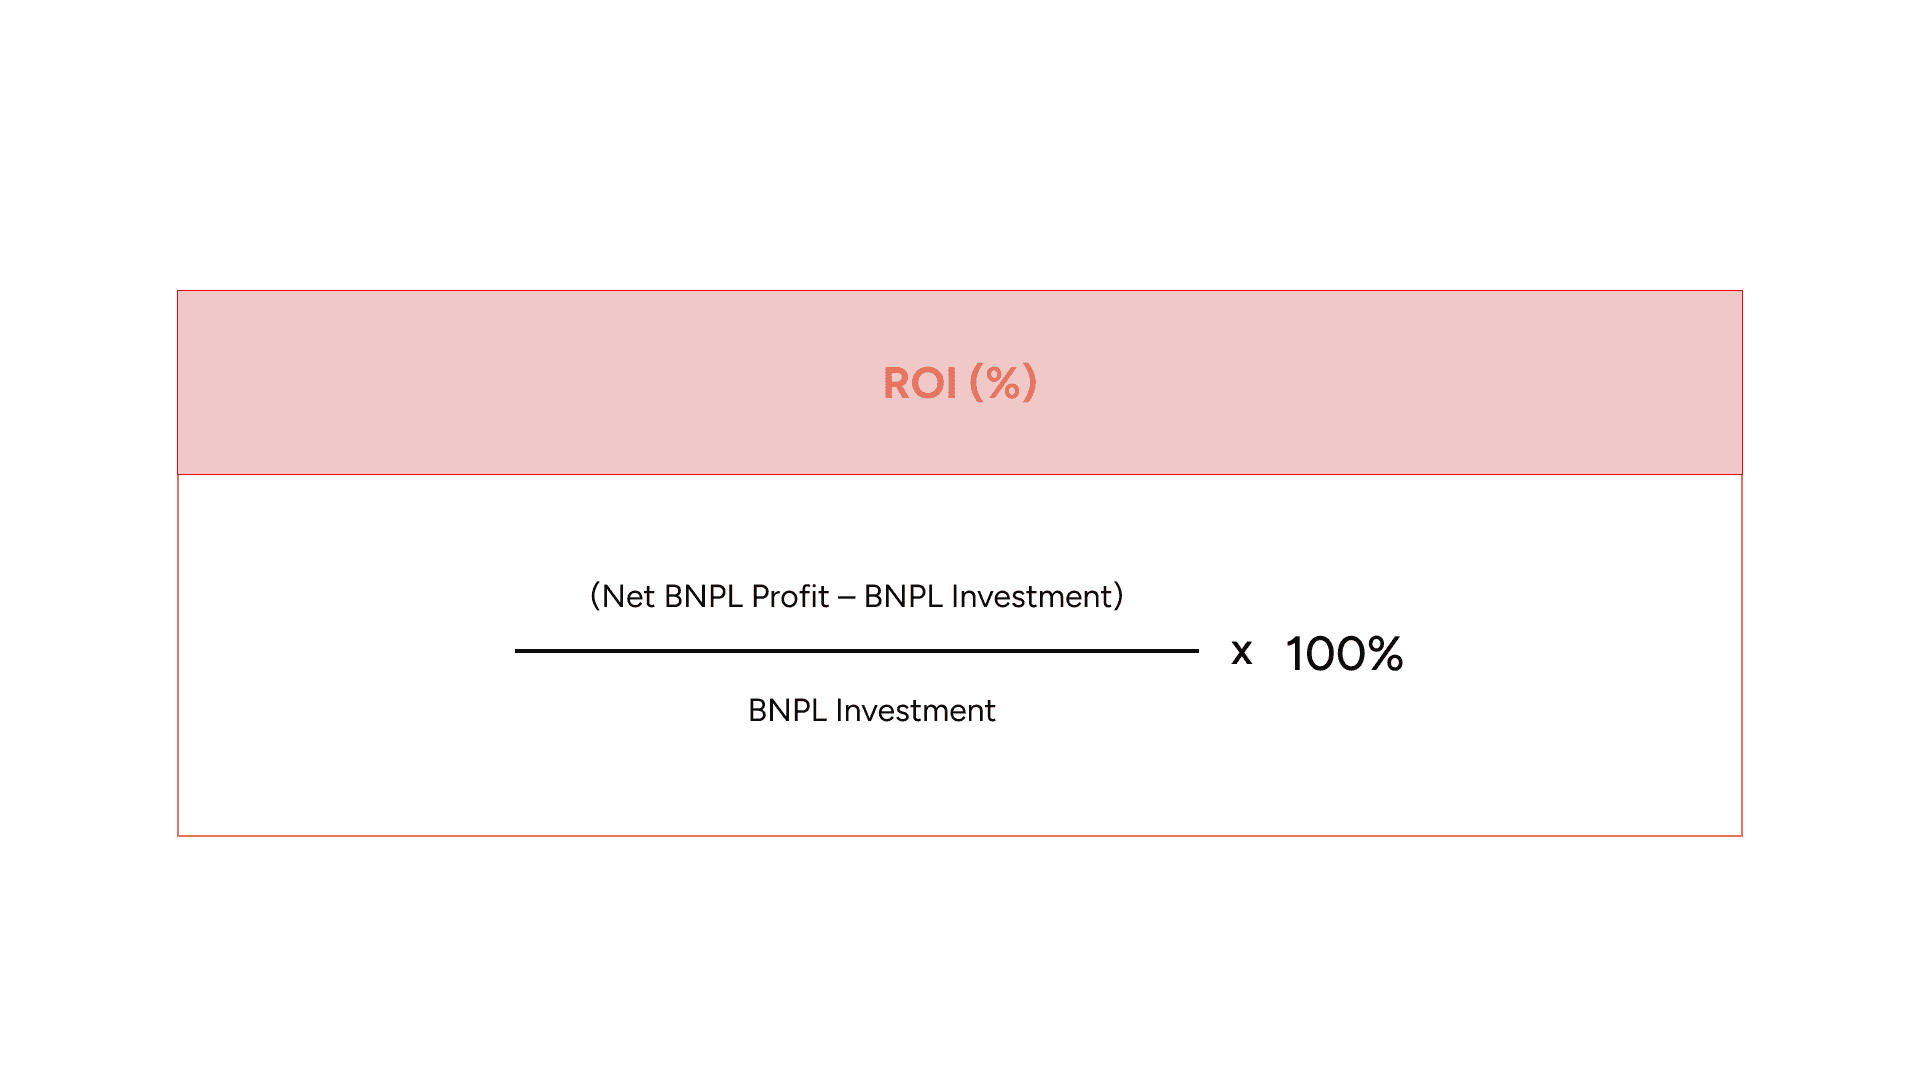
Understanding return on investment for BNPL requires enterprises to project revenue streams against the full spectrum of costs and risks. The ROI model should account for incremental revenue from merchant fees, consumer charges, and interest income, balanced against credit risk, fraud exposure, regulatory compliance expenses, and infrastructure investments.
Accenture previously estimated that embedding BNPL into credit card offerings could increase credit utilisation at large US banks from 21% to 26%, potentially lifting credit card income by 10%–16%.
The framework must capture both the opportunity—higher transaction volumes, expanded customer segments, reduced cart abandonment—and the reality that growth alone guarantees nothing. Grant Thornton emphasizes that U.S. lenders must integrate all cost strands and delayed repayment patterns into their forecasts as regulatory requirements tighten.
Strategic ROI modelling demands scenario planning across base, aggressive, and stressed cases, with conservative assumptions on default rates reflecting current consumer financial pressures and compliance burdens. Enterprises should measure time to profitability, not just velocity of growth, and align the model with their specific business context—retailers may prioritize conversion lift and order value over take-rate optimization.
Key variables include merchant take rates (2-6% of transaction value), repeat usage patterns that amortize acquisition costs, and the trade-offs between rapid scaling and sustainable unit economics. The model serves as both a financial tool and a strategic compass, informing decisions on merchant segmentation, underwriting standards, and expansion pace. Regular updates matter: competitive dynamics, regulatory evolution, and consumer behavior shifts will reshape assumptions, and enterprises that treat their ROI model as static will find themselves navigating with an outdated map.
Uncovering the Hidden Costs Of BNPL Apps After Go-Live
The most expensive part of BNPL apps begins after they go live. BNPL platforms must adapt to new compliance requirements, rising transaction volumes, and evolving consumer expectations. If these ongoing costs are ignored, your ROI projections can quickly fall apart.
1. Post-Launch Maintenance & Support
Ongoing maintenance ensures your BNPL platform remains secure, stable, and compliant. Regular updates, API upgrades, and feature enhancements protect uptime and user experience while adapting to regulatory shifts. The 2025 BNPL outlook highlights a market focused on “recovery, regulation, and reinvention”—where continuous improvements are not optional but essential for sustainable growth.
2. Third-Party Service Fees
Every external integration—payments, KYC/AML, and fraud detection—introduces recurring vendor costs. These services often charge per-transaction or monthly fees that rise with volume. Over time, vendor renewals, API usage surcharges, and compliance-driven adjustments can collectively add 20–30% to annual operating expenses.
3. Infrastructure & Scalability
As users and merchants scale, so do hosting, data storage, and processing demands. BNPL is transitioning into a “structured, compliant credit ecosystem,” requiring enterprise-grade cloud infrastructure and redundancy systems. This ongoing investment ensures performance, availability, and regulatory data retention across regions.
4. Ongoing Compliance & Security Costs
Regulators like the CFPB and FCA are tightening BNPL oversight, mandating affordability checks, transparency, and secure data handling. Continuous compliance audits, legal reviews, and system updates add measurable recurring costs but safeguard long-term credibility. Providers that embed compliance by design avoid re-engineering later—saving significant future expense.
5. Compliance & Legal Oversight
Evolving policies demand legal counsel, regulatory audits, and real-time reporting systems. These activities form a hidden yet critical expense, typically consuming 3–5% of annual operational budgets. Investing in proactive compliance avoids penalties and reinforces brand trust.
6. Partner and Merchant Servicing
As merchant partnerships grow, so do reconciliation, settlement, and reporting costs. Maintaining merchant satisfaction requires dedicated account management and automation tools. Over time, this becomes a predictable expense tied directly to transaction volume.
7. Customer Dispute Resolution
Disputes over repayments, chargebacks, or refunds increase as adoption scales. Efficient dispute handling needs automated workflows, trained support staff, and strong CRM systems. Without automation, these operations can consume up to 10% of yearly OPEX.
8. Data Storage, AI Monitoring, and Insurance Premiums
Massive transaction data requires secure, compliant storage and periodic AI model retraining. Combined with fintech insurance premiums against fraud or credit defaults, these costs grow steadily alongside platform expansion. Together, they represent a crucial but often overlooked component of long-term sustainability.
Post-launch success depends on planning for maintenance, vendor renewals, compliance, merchant support, and data resilience as ongoing cost centers. Enterprises that account for these hidden expenses early build scalable, trustworthy, and regulation-ready BNPL ecosystems with predictable ROI.
Most fintech founders underestimate the post-launch cost curve. The real ROI challenge is not development—it’s maintaining compliance, performance, and vendor relationships profitably.
 Kumar PratikFounder & CEO